Should You Sell First or Buy First in the Current Taranaki Property Market?

For homeowners looking to upsize, downsize or simply move across Taranaki, one of the biggest questions is often: Should we sell our current home first, or find and buy the next one first?
There isn't one answer that works for everyone. But there is one important point that buyers often overlook:
If you're selling and buying in the same market, what the overall property market is doing isn't necessarily the most important number. What really matters is the gap between the property you're selling and the property you're buying.
And in the current Taranaki market, where buyers generally have more choice and properties are taking longer to sell, understanding that gap can make a significant difference.
What is happening in the Taranaki property market?
The latest REINZ figures for August 2026 show an interesting market. Taranaki's median sale price was unchanged compared with August 2025. However, sales activity has slowed considerably. Taranaki recorded its lowest sales count since January 2025, and its lowest August sales count since 2021. Properties are also taking longer to sell, with Taranaki recording its highest August median Days to Sell since 2012.
That follows conditions we've seen throughout much of 2026: good levels of available stock, buyers having choice, and vendors needing to compete for that buyer attention. In July, for example, Taranaki had approximately 24 weeks of inventory, five weeks more than the same period a year earlier, while the regional median price was $590,000.
So while prices aren't necessarily falling sharply across the board, the balance of power in many parts of the market currently sits with the buyer. But that doesn't mean every property is behaving the same way.
The headline market isn't necessarily your market
This is one of the biggest mistakes property owners can make. They hear that the "Taranaki market" is flat, falling or improving and assume that figure applies equally to their own home and the property they want to buy. It doesn't.
A renovated family home in Fitzroy may behave very differently from an older property requiring work in another suburb. A modern brick home in Highlands Park may attract a different buyer pool from an investment property in Waitara. A quality lifestyle property may perform differently again.
Even within New Plymouth, two properties only a few streets apart can attract completely different levels of competition. Property markets don't move uniformly.
So if you're selling one property to buy another, you really have two separate markets to assess.
If you're upsizing in Taranaki
For someone looking to move into a more expensive property, a softer market can actually work in your favour. That might sound counterintuitive.After all, if your current home is worth less than it may have been a few years ago, surely you're worse off? Not necessarily.
Imagine you own a property that might have previously been worth $700,000, and you're looking to purchase a larger home that was worth around $1,000,000.
Your gap is $300,000. Now imagine both properties fall by 5%.
Your $700,000 property falls by approximately $35,000.
But the $1,000,000 property falls by approximately $50,000.
You've technically lost $35,000 on the property you're selling, but potentially saved $50,000 on the property you're buying.
The gap has reduced by $15,000.
That is why people looking to upsize can sometimes benefit from making their move in a softer market. The opposite can happen when the market rises. Your current property might increase in value, which feels great, but the more expensive property you're trying to buy may increase by considerably more in dollar terms.
Don't focus only on what you've "lost"
This is where psychology can get in the way. A homeowner might think: "My property would have sold for $800,000 a couple of years ago and now I might only get $740,000. I'm not selling for that."
That's understandable. But there's another question that needs to be asked: What has happened to the property you want to buy?
If the $1.2 million property you wanted two years ago can now be bought for $1.05 million, focusing solely on the $60,000 reduction in your sale price misses the bigger picture.
You've lost $60,000 on one side of the transaction. But potentially gained $150,000 of purchasing power on the other.
The number that matters isn't simply your sale price. It's the changeover figure.
If you're downsizing
Downsizers need to look at the equation slightly differently. If you're selling a more expensive property and buying something cheaper, a rising market can potentially work in your favour because your higher-value property may gain more in dollar terms. But again, broad market statistics only tell part of the story.
For example, someone selling a large family home in a tightly held New Plymouth suburb and moving into a smaller townhouse may be dealing with two completely different levels of supply and demand. Quality, low-maintenance homes can sometimes attract very strong competition from downsizers. So while the property you're selling may have performed well, the type of property you're trying to secure may also be scarce.
That's why downsizing shouldn't simply be viewed as:
Sell expensive house → buy cheaper house → pocket the difference.
You need to understand the depth of the market for both properties.
The biggest risk of selling first
Selling first gives you one major advantage: certainty.
You know exactly how much money you have available. Your finance becomes clearer. And when you find the right property, you can potentially negotiate without needing to make your purchase conditional on selling your existing home. That can make you a significantly stronger buyer. But there is an obvious downside.
What if you sell and can't find anything you actually want to buy?
Suddenly settlement is approaching and the pressure starts building. That pressure can cause buyers to compromise. Maybe it's the wrong street. Maybe it doesn't have the second living area you wanted. Maybe the section isn't right. Maybe you're paying more than you should because you feel like you need somewhere to go.
That is when selling first can become expensive. The solution isn't necessarily to avoid selling first.
It's to have a strategy before your property goes on the market.
That could include negotiating a longer settlement, arranging temporary accommodation if required, and importantly, beginning your property search well before your own home sells.
The biggest risk of buying first
Buying first removes one major uncertainty. You've secured the property you actually want. For certain properties, that can be extremely important.
If you've spent six months looking for a particular type of home in Fitzroy, Strandon or Merrilands and the right property finally appears, waiting until you've sold your own property may mean losing it. But buying first creates another risk. Financial pressure.
You need to understand whether you can genuinely hold two properties if necessary. That may involve bridging finance, servicing two mortgages temporarily, additional rates and insurance, or accepting a lower price on your existing property because you suddenly need it sold. And that's the danger.
The moment you need to sell, your negotiating position changes.
Before buying first, talk to your bank or mortgage adviser and understand exactly what the worst-case scenario looks like — not simply the ideal scenario where your property sells immediately.
There is another option: coordinate both
Where possible, the ideal outcome can be to coordinate the sale and purchase together. It isn't always easy. But with the right planning, settlement dates and conditions can sometimes be structured to reduce the risk on both sides.
For example, you may negotiate a longer settlement when selling your existing property. You may secure your next property with settlement aligned to your sale. Or you may begin searching months before selling so that you understand exactly what is available before committing.
The important part is planning the two transactions together rather than treating them as completely separate decisions.
In the current Taranaki market, buyers have an advantage
The current environment creates an interesting opportunity. Properties are generally taking longer to sell, sales volumes are relatively low, and buyers have had good levels of stock to choose from. That can create negotiating opportunities. But it doesn't mean every vendor is desperate to sell. And it certainly doesn't mean every property should be bought simply because the market favours buyers.
Good property can still attract strong competition. We've seen properties receive multiple offers while others nearby sit unsold for weeks or months.
The difference is often the property, position, presentation and price. That's why buying based purely on a regional median is dangerous.
The best move in a softer market
If you're selling and buying, the strongest opportunity is often: Sell something that has held its value relatively well and buy something where you can negotiate harder.
To understand whether that opportunity exists, you need to look at both sides of your move.
That means assessing:
recent comparable sales, rather than asking prices
the property type you're selling versus the property type you're buying
the level of available competing stock
how long comparable properties are taking to sell
vendor expectations and motivation
the amount of buyer competition
properties that have failed to sell
price reductions and withdrawn listings
pre-market opportunities
off-market properties that never appear online
That's far more useful than trying to predict whether the overall Taranaki market will rise or fall another few percent.
Where a buyer's agent can help
Buying while selling can be stressful because you're effectively managing two major property transactions at once. Your salesperson's job is to achieve the best possible outcome for you as the seller of your existing property.
Our job is different. We represent you as the buyer of the next one.
At The Finders, we can begin searching while your property is being prepared for sale, assess listed, pre-market and off-market opportunities, inspect properties, analyse comparable sales, complete due diligence and negotiate the purchase on your behalf. That becomes particularly valuable when you're under time pressure.
Instead of beginning your search after you've sold, you can already have a clear brief, understand the target market and know what properties are worth. And if the right opportunity appears before your property sells, you can make the decision based on the numbers rather than emotion.
So, should you sell first or buy first?
There is no universal answer.
Sell first if knowing exactly what you have available to spend is important, your borrowing capacity is tight, or carrying two properties would create financial pressure.
Buy first if you have the financial capacity to comfortably hold both properties for a period and the property you're looking for is particularly scarce or difficult to replace.
Coordinate both if your financial position and the contracts allow it. With the right settlement periods and planning, this can often produce the cleanest outcome.
But don't make the decision based solely on whether you think the Taranaki property market is going up or down. Look at the two properties involved.
What are you selling?
What are you buying?
How are those two particular markets performing?
And most importantly:
What is the gap between them?
Because if you're buying and selling in the same market, the changeover figure can matter far more than the headline property price.
Thinking about selling and buying in Taranaki?
Whether you sell first or buy first, the key is having a strategy for both sides of the move. And importantly, don't limit your search to what you can see advertised online.
At The Finders, 81% of the properties we have purchased for our clients have been off-market, properties that weren't publicly advertised for sale when we secured them.
That can be particularly valuable when you're selling and buying at the same time. Instead of waiting for the right property to appear online, we're actively searching the wider market, speaking directly with salespeople, property owners and our network to uncover opportunities that may otherwise never reach you.
At The Finders, we work exclusively for the buyer. We help establish your buying strategy, search listed, pre-market and off-market opportunities, inspect and assess properties, analyse comparable sales, coordinate due diligence, negotiate the purchase and help manage the process through to settlement.
So before deciding whether to sell first or buy first, understand both sides of the equation.
What are you selling?
What are you buying?
What is the gap between the two?
And are you seeing the whole market, or just the properties advertised online?
Because in our experience, some of the best opportunities aren't necessarily the ones you see on the property portals.
81% of our client purchases have been off-market.
Find it. Assess it. Negotiate it. Due diligence it. Secure it.
The Finders — Taranaki's Property Buyer's Agency.
This article provides general information only and should not be relied upon as financial, legal or lending advice. Individual circumstances differ. Buyers should obtain independent legal and financial advice before entering into a property transaction.
Thinking about buying property in Taranaki?
Whether you're just starting to look, have already found a property, or simply want to know what your options are, Thomas is happy to have a chat.
The first conversation is free, there's no obligation, and no pressure to proceed. Just straightforward advice from someone who knows the Taranaki market.
More Buyer Insights










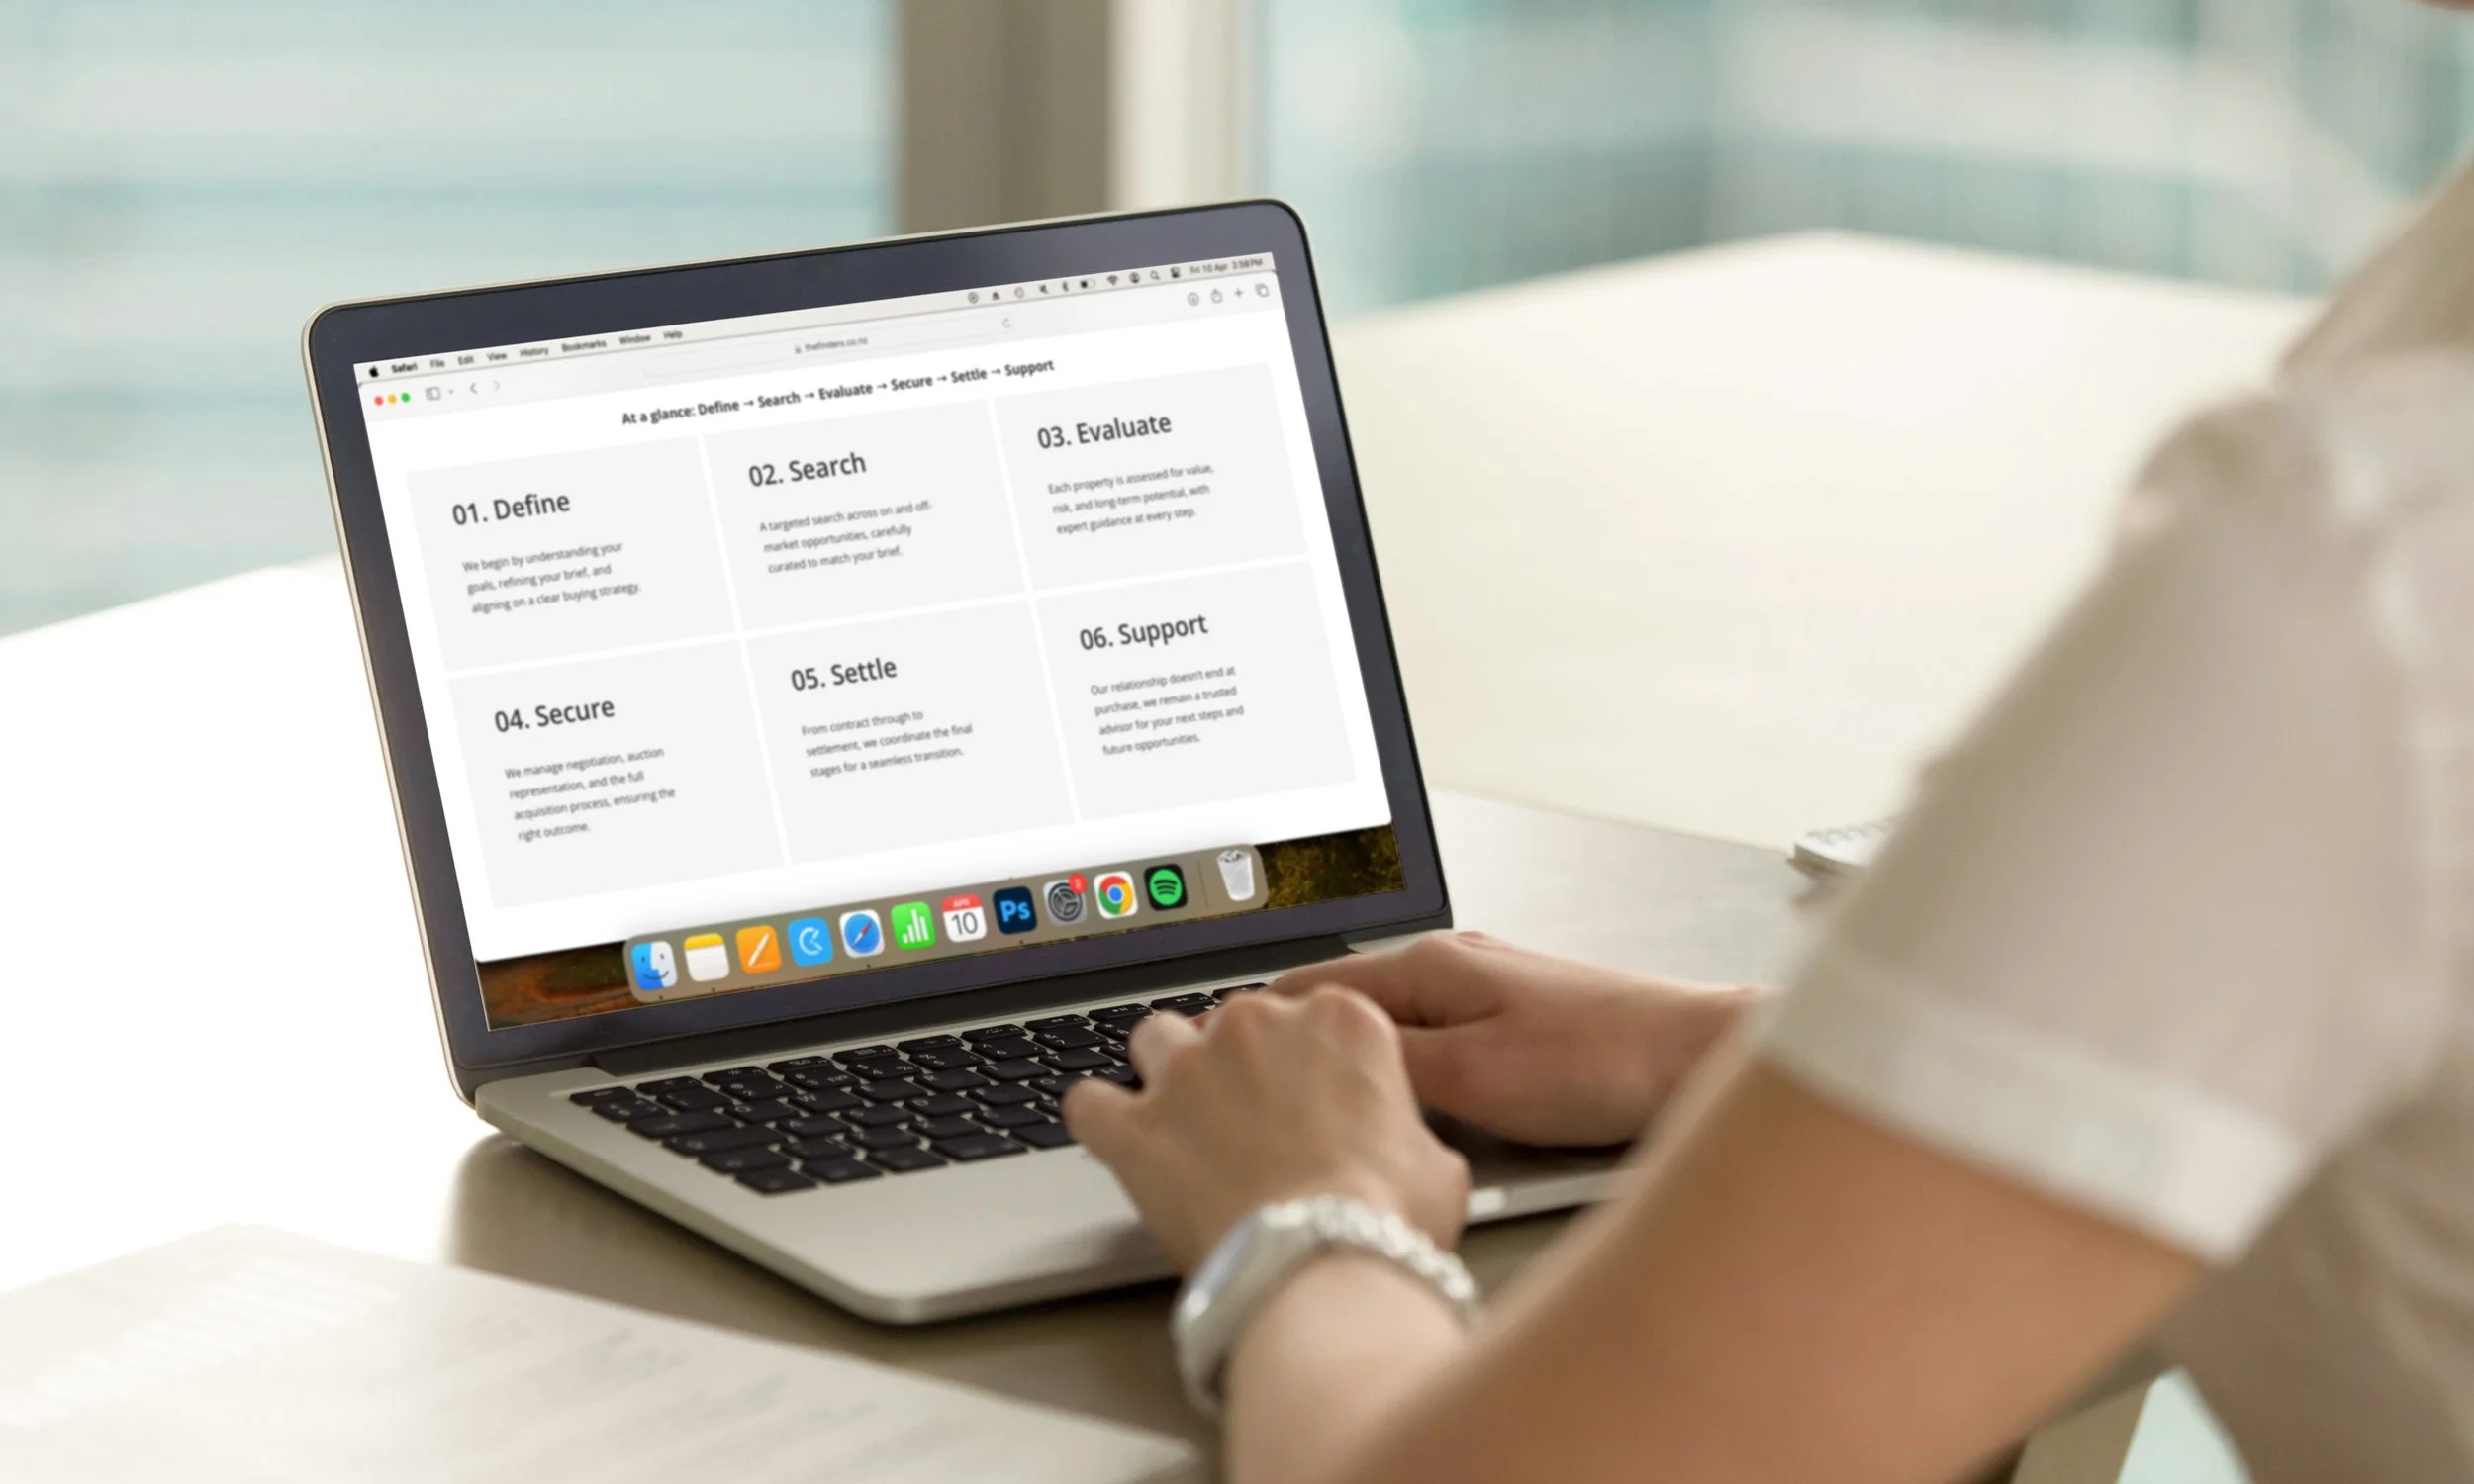
Selling your home and buying another in Taranaki? Find out whether you should sell first, buy first or coordinate both, and why the gap between the two properties may matter more than the overall market.